Key takeaways
- San Marcos sits on the Balcones Escarpment in "Flash Flood Alley," and NOAA lists 127 flash flood reports for Hays County.
- During the Memorial Day 2015 flood, the Blanco River at Wimberley rose from about 5 feet to about 41 feet in roughly four hours.
- Standard homeowners and commercial policies generally exclude flood; NFIP or private flood policies fill that gap.
- NFIP coverage usually starts 30 days after purchase, and FloodSmart says to submit claim documentation within 60 days of the flood unless your insurer gives another timeframe.
- New FEMA flood maps for San Marcos took effect January 17, 2025. Check your zone, even if you were not in one before.
- Many San Marcos losses involve both flood and non-flood water damage, and sorting out which policy pays for what is where careful documentation matters most.
Few places in Texas know floodwater like San Marcos. The city sits where the Hill Country drops off the Balcones Escarpment, and heavy rain on the steep, thin-soiled terrain to the west can send the Blanco River, the San Marcos River, and local creeks up with very little warning. This guide covers flood damage insurance claims in San Marcos: the floods that shaped the area, how flood coverage differs from ordinary water damage coverage, how National Flood Insurance Program (NFIP) policies work, what changed with the 2025 flood maps, and how to protect your claim.
Flash Flood Alley: San Marcos flood history
NOAA's Storm Events Database lists 127 flash flood reports and 12 flood reports for Hays County. Flooding can happen in any season, but reports cluster in late spring and fall: June (28 combined flash flood and flood reports), May (24), and October (21) lead the list. Several of those events caused major damage and led to federal disaster declarations.
| Event | What official sources recorded | FEMA declaration |
|---|---|---|
| October 17–18, 1998 | NWS estimated over 30 inches of rain over a small area south of San Marcos in 36 hours | DR-1257 |
| Halloween flood, October 30–31, 2013 | 6–10 inches across Hays County, 12–14 inches from Wimberley to Driftwood; the San Marcos River flooded near Martindale | DR-4159 |
| Memorial Day flood, May 23–24, 2015 | Blanco River at Wimberley rose from about 5 ft to about 41 ft in roughly four hours; San Marcos River near San Marcos crested at 43.08 ft | DR-4223 |
| October 30–31, 2015 | Two-day rain totals of 18.46 inches near Buda and 15.63 inches north of San Marcos | DR-4245 |
| April 11, 2017 | Up to 8 inches of rain in San Marcos; I-35 frontage roads closed and about 60 water rescues reported | None |
The Memorial Day flood of 2015
The National Weather Service summary of the May 23–24, 2015 flood describes how quickly it unfolded. Rain of 12 to 13 inches fell in the Blanco River headwaters over four to six hours. At Wimberley, the river rose from about 5 feet around 9 p.m. to about 41 feet by 1 a.m., climbing roughly 5 feet every 15 minutes for an hour of that time. The NWS issued Flash Flood Emergencies for Wimberley and then San Marcos, and the San Marcos River near San Marcos crested at 43.08 feet early on May 24. The flood was part of FEMA disaster declaration DR-4223.
Five months later, storms on October 30, 2015 dropped rain at rates of 7 inches or more per hour in parts of the county, according to NCEI records, flooding the Blanco River, Onion Creek, Plum Creek, and the San Marcos River again. Since then, the city has used federal HUD disaster recovery (CDBG-DR) funds for flood mitigation, including the Blanco River Flood Mitigation Project. For more local events, see our San Marcos storm history and recent weather events pages.
Why Hays County floods so fast
Three local features explain why flooding here is so sudden. First, the Hill Country west of I-35 has thin soils over limestone, so heavy rain runs off quickly instead of soaking in. Second, rivers such as the Blanco gather that runoff from a large upstream area and funnel it through narrow valleys toward Wimberley and San Marcos. Third, rapid growth along the I-35 corridor has added roofs, driveways, and streets that shed water into local creeks. East of the interstate, expansive clay soils drain slowly, so water can pond around slab foundations after a long rain. The result is a county where a creek can leave its banks within an hour and low water crossings close often. If you live upstream, our Wimberley and Buda pages cover local details for those communities.
Flood damage vs. water damage: which policy pays?
This is the most important question in almost every flood damage insurance claim in San Marcos. Insurance policies treat "flood" and "water damage" very differently, and the wording of your policy controls. In general terms:
| Situation | Usually handled by | Notes |
|---|---|---|
| River or creek overflows and water enters the home | Flood policy (NFIP or private) | Excluded under standard homeowners policies |
| Heavy rain causes surface water to pool and flow in through doors or walls | Flood policy | Rising surface water is generally treated as flood |
| Wind or hail opens the roof and rain pours in | Homeowners or commercial policy | The opening usually must be caused by a covered peril |
| Pipe suddenly bursts inside the wall | Homeowners or commercial policy | Typically "sudden and accidental" discharge; long-term leaks are often excluded |
| Sewer or drain backs up into the house | Depends on endorsement | Often excluded unless you bought water backup coverage |
| Groundwater seeps through the slab | Often excluded | Seepage is commonly excluded in both types of policy; check wording |
A single storm can produce more than one of these. For example, wind may damage a roof while rising water enters the first floor. In that case two policies and two adjusters may be involved, and damage needs to be documented and separated carefully so that each insurer pays its share and neither can point at the other. For non-flood water losses, see our water damage claims page.
NFIP flood insurance basics
The City of San Marcos participates in the National Flood Insurance Program, which means property owners in the city can buy NFIP flood policies through an agent. Private flood policies are also available and may have different terms. Here is how NFIP coverage works according to FloodSmart.gov:
| NFIP feature | Homeowner policy | Commercial policy |
|---|---|---|
| Building coverage limit | Up to $250,000 | Up to $500,000 |
| Contents coverage limit | Up to $100,000 | Up to $500,000 |
| Deductibles | Building and contents are purchased separately and carry separate deductibles | |
| Waiting period | Typically 30 days after purchase, with limited exceptions | |
The 30-day waiting period
Because NFIP coverage normally starts 30 days after you buy it, you cannot wait until the Blanco is rising to purchase a policy. FloodSmart lists a few exceptions, including policies bought when making, increasing, extending, or renewing a mortgage, and a one-day wait when a property is newly placed in a high-risk flood zone and the policy is purchased within 12 months of the map change.
What NFIP does not cover
FloodSmart lists items NFIP policies do not cover regardless of the cause of flooding, including temporary housing and additional living expenses, landscaping, septic systems, decks, patios, fences, swimming pools, most self-propelled vehicles, currency and valuable papers, and personal property kept in basements. That gap surprises many people, especially those used to homeowners policies that pay additional living expenses.
Proof of loss and claim deadlines
Check your policy for the exact deadline that applies to you. FloodSmart's claims checklist says to submit all required documentation to support your claim within 60 days of the flood, or within the timeframe your adjuster or insurance provider gives you. If you discover more damage later, you can request an additional payment. If your claim is denied, FloodSmart explains that you can appeal to FEMA within 60 days of the date on the denial letter. NFIP deadlines are strict, so keep copies of everything you submit and note the date.
The January 17, 2025 San Marcos flood maps
After a revision process that began in 2016, new FEMA flood maps for San Marcos took effect on January 17, 2025, according to the City of San Marcos. The update covers the Blanco River, the San Marcos River, and portions of Sink, Purgatory, Willow Springs, and Cottonwood Creeks. The city reports that more than 341 acres within San Marcos lie in a Special Flood Hazard Area.
What this means for you:
- Look up your property. Use the city's floodplain GIS map or the FEMA Flood Map Service Center to see your current zone.
- Your lender may require coverage if your building is now in a high-risk zone and has a federally backed mortgage.
- Outside the zone does not mean safe. Flash flooding along streets and small creeks happens outside mapped floodplains, as the April 2017 street flooding in San Marcos showed.
How to document a flood claim
- Stay safe first. Do not enter a flooded building until it is safe, and be cautious with electricity and gas.
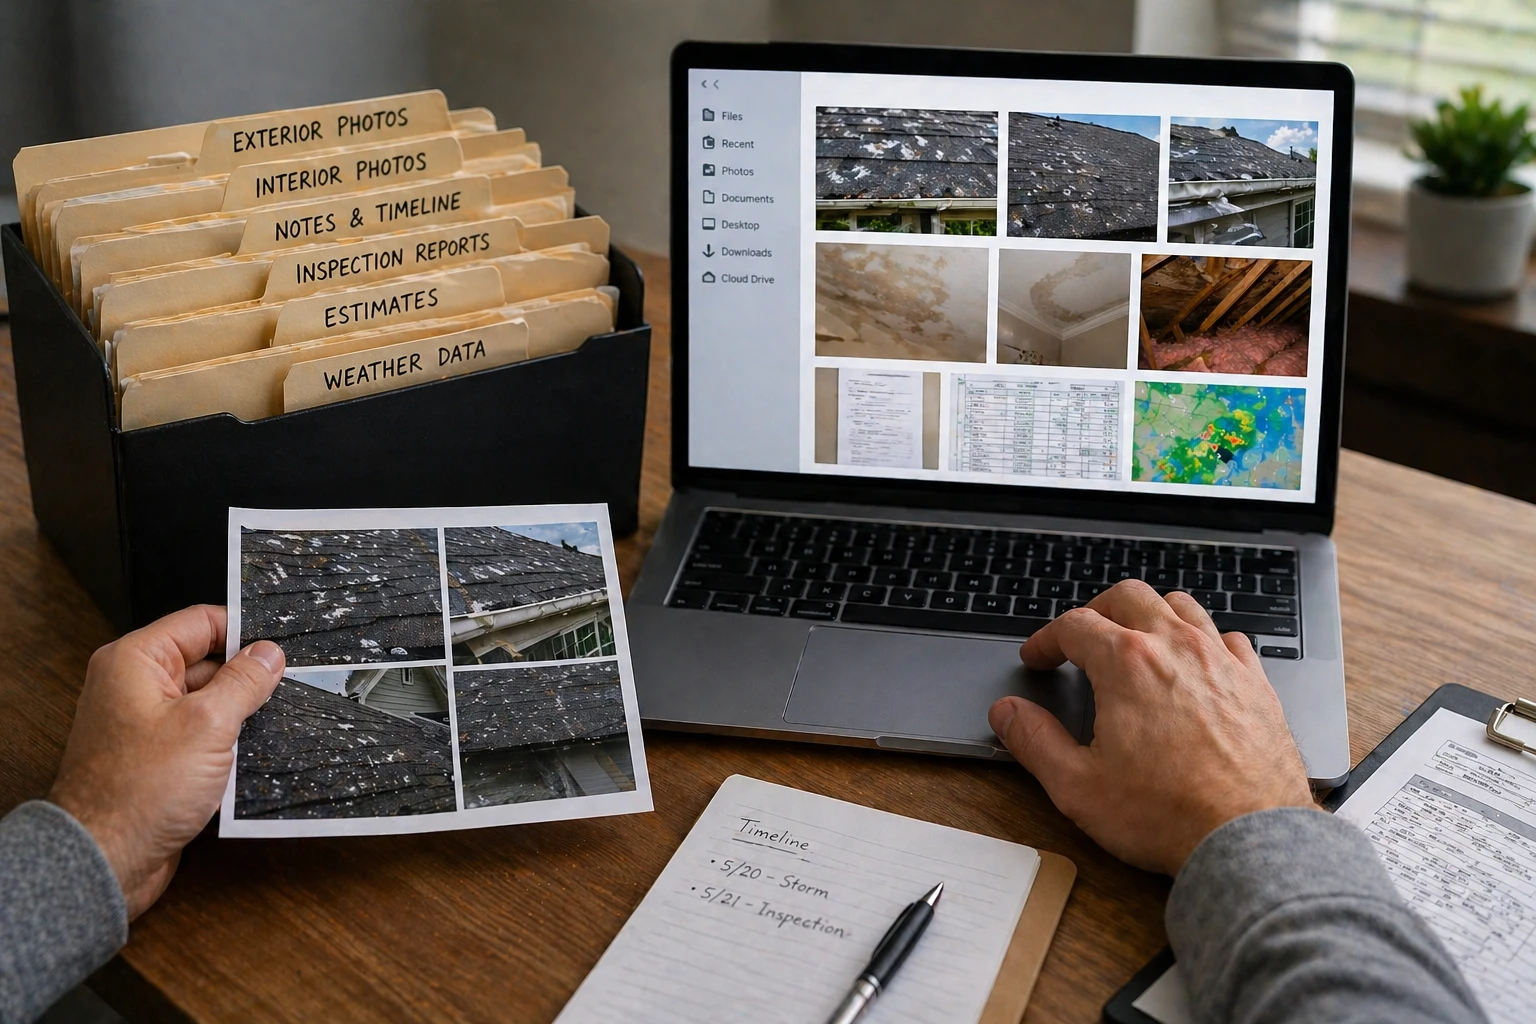
- Photograph and video everything before cleanup, including the high-water line on walls, damaged flooring, appliances, and the outside of the building.
- Measure the water line inside and outside. It helps establish the extent of the damage.
- Keep samples of carpet, flooring, and drywall where practical, and list damaged contents with brand, age, and approximate value.
- Start drying out. Remove standing water and wet materials when it is safe, and keep receipts for fans, dehumidifiers, and mitigation work.
- Report the claim promptly to your flood insurer and, if wind or other damage is involved, to your homeowners insurer too.
Our claim documentation checklist has a printable version.
What a San Marcos public adjuster can do on a flood claim
Flood claims involve strict deadlines, a dense policy form, and frequent overlap with other coverage. A licensed San Marcos public adjuster works for the policyholder and can help by:
- Reviewing your flood and property policies to see which coverage applies to each part of the loss.
- Documenting the building and contents damage and preparing a detailed estimate.
- Helping assemble the proof of loss and supporting documents within the required timeframe.
- Separating flood damage from wind or plumbing damage when more than one policy is involved.
- Requesting additional payment when damage was missed, or helping you prepare for an appeal of a denied claim.
We cannot promise a particular outcome, and we do not give legal advice; for questions about lawsuits or legal deadlines, talk with a Texas attorney. Fees are disclosed in a written contract before any work begins, and Texas law caps public adjuster compensation at 10% of the insurance settlement.
If you are dealing with flood or water damage in San Marcos, Wimberley, Buda, or elsewhere in Hays County, read more about our flood damage claims service or request a free claim review. As a San Marcos Public Adjuster serving San Marcos, Hays County, and surrounding Central Texas communities, we can help you understand where you stand before the deadlines close in.
Frequently Asked Questions
Does homeowners insurance cover flood damage in San Marcos?
Generally, no. Standard homeowners and commercial property policies exclude flood, meaning surface water that rises and enters the building. Flood coverage usually comes from a separate National Flood Insurance Program (NFIP) policy or a private flood policy. Water damage from a sudden burst pipe or wind-driven rain through a storm-damaged roof is a different situation and may be covered under your homeowners policy.
How long is the waiting period for NFIP flood insurance?
According to FloodSmart, NFIP coverage typically goes into effect 30 days after purchase. There are exceptions, such as buying a policy in connection with making, increasing, extending, or renewing a mortgage, and a one-day wait when a property is newly mapped into a high-risk flood zone and the policy is bought within 12 months of the map update.
How long do I have to submit a flood claim proof of loss?
Check your policy. FloodSmart's claims checklist says to submit all required documentation to your insurance provider within 60 days of the flood, or within the timeframe your adjuster or insurance provider gives you. Ask your adjuster about any extension in writing if you need more time.
Did the San Marcos flood maps change?
Yes. New FEMA flood maps covering the Blanco River, the San Marcos River, and portions of Sink, Purgatory, Willow Springs, and Cottonwood Creeks took effect on January 17, 2025, according to the City of San Marcos. You can check your property using the city's floodplain GIS map or the FEMA Flood Map Service Center.
What does NFIP flood insurance cover?
NFIP homeowner policies offer building coverage up to $250,000 and contents coverage up to $100,000, purchased separately with separate deductibles. Some items are not covered, such as temporary housing costs, landscaping, fences, decks, and most property in basements. Read your policy for the full list.
Can I appeal a denied NFIP flood claim?
Yes. FloodSmart explains that you can file an appeal with FEMA within 60 days of the date on your denial letter. You can also request additional payment if you find damage that was missed. For questions about lawsuits or legal deadlines, consult a Texas attorney.
Sources and further reading
- NWS Austin/San Antonio: Memorial Day 2015 flood summary
- FloodSmart: Buy a flood insurance policy (coverage limits and waiting period)
- FloodSmart: Flood insurance claims checklist
- City of San Marcos: FEMA Flood Map Revision Process
- FEMA DR-4223: Texas Severe Storms, Tornadoes, Straight-line Winds, and Flooding (2015)
This article is general information about property insurance claims in Texas, not legal advice, and not a promise of any coverage or outcome. Your policy language and the facts of your loss control your claim.