
Many property claims are estimated from the outside, before anyone pulls off a shingle or opens a wall. Then the work starts and the real scope shows up: soft decking, wet insulation, a cracked rafter, or a code requirement the first estimate did not include. Insurance claim supplements in San Marcos are how those additional items are documented and presented to the insurer. As a San Marcos public adjuster, we help property owners identify what was missed, tie each item to the original loss, and submit it in a form the insurer can review.
What a Supplement Can Cover
| Supplement type | Example | Documentation that helps |
|---|---|---|
| Hidden damage | Water-damaged decking under hail-damaged shingles; wet framing behind siding | Photos during tear-off before the area is closed up, with measurements |
| Missed items | Gutters, vents, flashing, screens, fences, or interior ceilings not in the estimate | Photos of each item and its location on a diagram |
| Quantity corrections | Roof squares, waste factor, ridge or eave lengths measured short | Independent measurements or a roof report |
| Code-required work | Items required by current codes when repairing covered damage | Permit records, code citations, and ordinance or law coverage review |
| Pricing adjustments | Specialty materials or trades priced below local cost | Itemized local invoices and supplier quotes |
| Additional living or business costs | Longer displacement or shutdown than first estimated | Receipts, leases, and a revised timeline |
Why Supplements Are Common in San Marcos Claims
Hays County roofs see a lot of spring weather; NOAA records 180 hail reports in the county since 1967, peaking in April and May. Large events like the May 9, 2024 storm, which dropped 3-inch hail west of San Marcos, send many adjusters into the field at once, and quick first inspections can miss items that only show up later.
Construction details matter too. Under the 2021 codes the City of San Marcos has enforced since April 1, 2023, some repairs require upgrades that a basic replace-in-kind estimate leaves out. The city's local amendment means a roof covering replacement does not need a permit unless the new roof is heavier than the existing one, but other work, such as structural or interior repairs, may need permits. Whether code costs are payable depends on your ordinance or law coverage. Our local building codes page summarizes the details, and nearby cities like Kyle and Buda have their own permit offices.
The Supplement Process, Step by Step
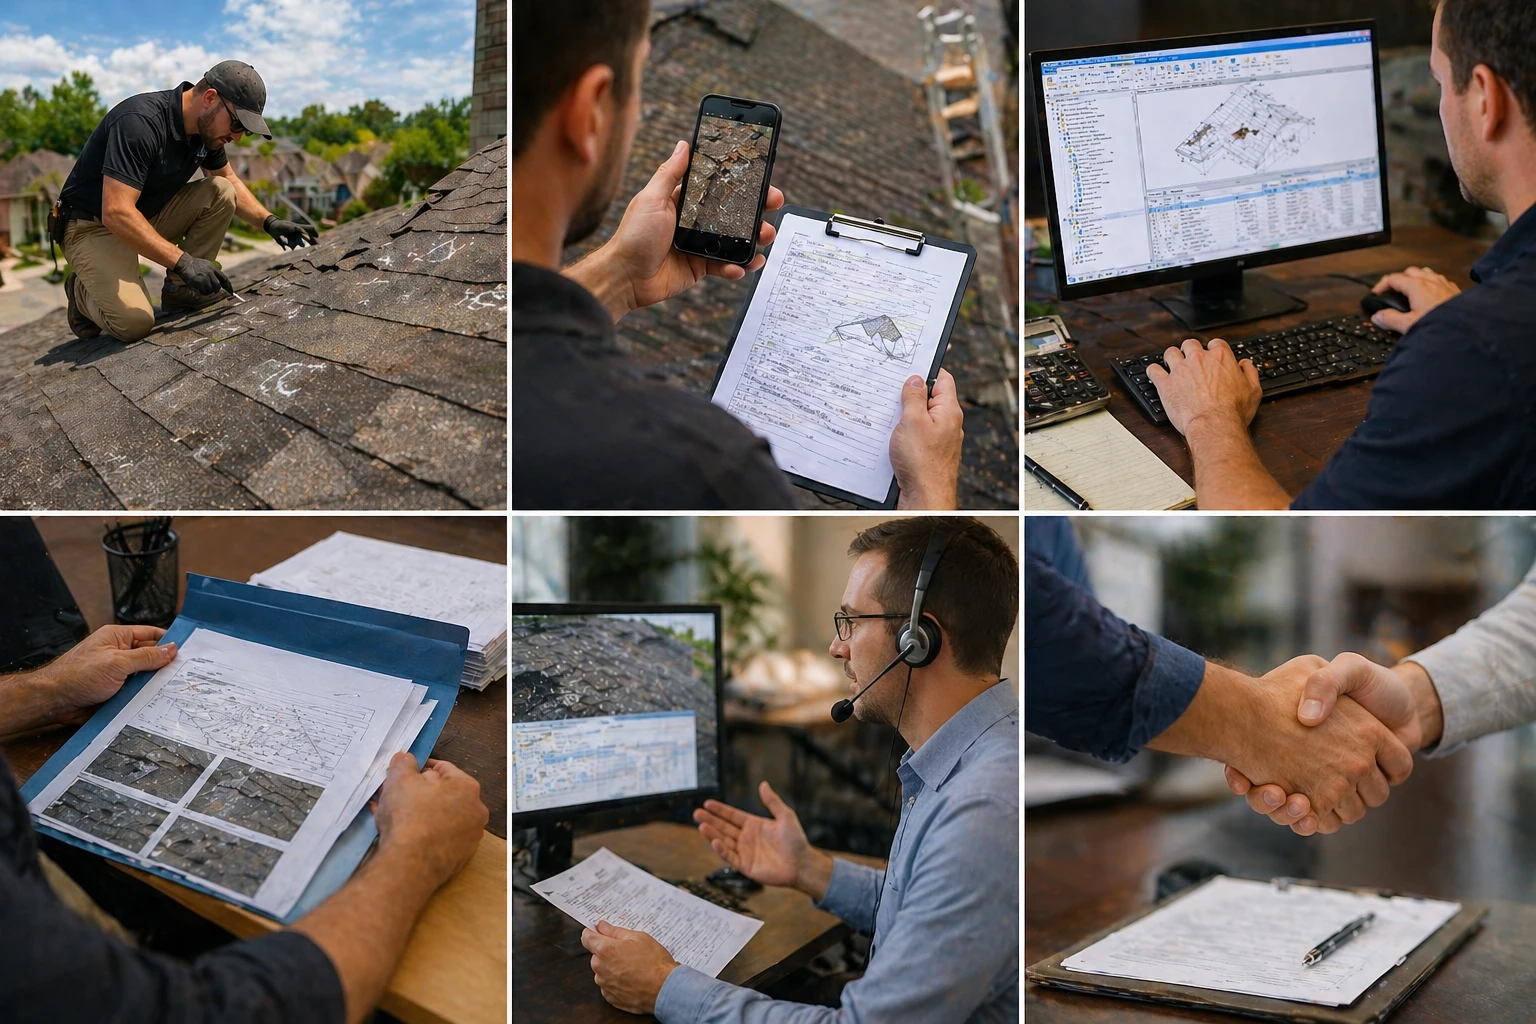
- Stop and document. When hidden damage appears, photograph it in place, measure it, and note its location before it is repaired or covered.
- Notify the insurer. Tell the adjuster promptly and offer an opportunity to re-inspect. Many policies have notice and inspection conditions.
- Prepare the request. Each added item should appear as a line item, with quantity, price, and the photo or measurement that supports it. We prepare these in Xactimate so they line up with the insurer's estimate.
- Explain the connection. Show how each item relates to the covered loss. Rotted decking from years of slow leaks is a different matter from decking soaked through new hail damage.
- Follow up in writing. Track the response, answer questions, and respond to any items the insurer declines.
Reopening a Previously Settled Claim
Sometimes the additional damage turns up after the claim has already been paid and closed. A homeowner starts a remodel and finds water-stained framing beneath a previously repaired roof leak, or a business owner discovers interior damage months after a storm. Many insurers will consider reopening a closed claim for additional damage from the same event, and many policies set a time limit on doing so.
Whether a reopened claim succeeds depends on several things:
- Timing: any deadline in the policy for reopening or supplementing a claim.
- Connection: evidence that the new damage came from the same covered loss, not later wear or a separate event.
- Releases: whether you signed a document releasing further claims. If you did, talk to a Texas attorney.
- Documentation: the original estimate and payments, plus clear new photos and measurements.
A closed claim is not automatically final, but reopening is never guaranteed either. If the original settlement was simply too low for the damage that was already known, see underpaid insurance claims.
Supplements and Recoverable Depreciation
On many replacement cost policies, the insurer pays actual cash value first and holds back depreciation until repairs are complete. Requesting that recoverable depreciation is a separate step from a supplement. When you finish repairs, you may need to send invoices for the completed work to release the held-back depreciation, and also submit a supplement for anything new. Watch the policy deadline for claiming depreciation. Our article on replacement cost vs. actual cash value explains the mechanics.
Common Supplement Mistakes to Avoid
- Covering up damage before it is documented. Once new decking or drywall is installed, the evidence is gone. Photograph first, with a tape measure in the frame.
- Submitting a lump sum. A single figure from a contractor is hard for an insurer to evaluate. Line items with quantities and prices are easier to review.
- Mixing old and new damage. Including pre-existing deterioration alongside storm damage can undermine the credibility of the whole request.
- Missing the policy deadline. Supplements, reopening requests, and depreciation claims can each have time limits.
- Losing track of what was sent. Keep copies of every submission and the insurer's response to each item.
How a San Marcos Public Adjuster Helps With Supplements
We review the original estimate, inspect the property, and document missed or hidden damage. We prepare supplemental line items with supporting photos and measurements, communicate with the adjuster, and track each item until it is resolved. If the insurer and policyholder still disagree on the amount, insurance appraisal may be an option to discuss. For a fresh look at what the first estimate included, see insurance estimate review, and for hail roofs specifically, our article on hail damage claim supplements.
Fees are disclosed in a written contract before any work begins; Texas law caps public adjuster compensation at 10% of the insurance settlement. We cannot guarantee that supplemental items will be paid. If you have found more damage, a licensed San Marcos public adjuster can help you sort out the next step. Request a Free Claim Review.
Frequently Asked Questions
What is an insurance claim supplement?
A supplement is a request to add items or cost to an existing claim. It usually covers damage found after the first inspection, items the original estimate left out, quantity corrections, or code-required work. Each item needs documentation showing it relates to the covered loss.
Do I need to tell the insurer before my contractor fixes hidden damage?
It is usually wise to notify the insurer as soon as hidden damage is found and give it a chance to inspect before the area is covered up. At a minimum, photograph and measure everything first. Check your policy for specific notice requirements.
Can a supplement be filed after the claim is closed?
Often an insurer will consider reopening a closed claim for additional damage from the same loss, but many policies set a time limit, and a signed release may limit your options. Ask the insurer about its reopening process and act promptly.
Is a supplement the same as recoverable depreciation?
No. Recoverable depreciation is money already in the estimate that the insurer held back until repairs are completed. A supplement adds new scope or cost that was not in the estimate. You may need to request both, separately.
Can my roofer handle the supplement?
Contractors often submit supplements for the work they perform. Texas law limits contractors from acting as public adjusters or negotiating claims on a property owner's behalf. A licensed public adjuster represents you on the claim itself, while your contractor handles the repairs.
Will the insurer approve every supplemented item?
Not necessarily. The insurer will review whether each item relates to the covered loss and is reasonably priced. Clear photos, measurements, and explanations improve the chance that items are understood, but no outcome is guaranteed.