
Flood damage insurance claims in San Marcos are different from almost every other property claim. The policy is usually separate from your homeowners coverage, the rules come largely from the federal flood program, and the deadlines are strict. Whether water came from the Blanco River, the San Marcos River, a creek like Sink or Purgatory, or sheets of runoff across a neighborhood, the first questions are the same: what kind of water was it, and which policy responds? As a San Marcos public adjuster, we help homeowners and businesses answer those questions and assemble a complete claim.
Flood History Along the Blanco and San Marcos Rivers
Hays County sits along the Balcones Escarpment, and NOAA lists 127 flash-flood reports for the county, most often in June, May, and October. Several floods shaped how the community thinks about risk:
- Memorial Day flood, May 23–24, 2015: the Blanco River at Wimberley rose from about 5 feet to about 41 feet in roughly four hours, and the San Marcos River near San Marcos crested at 43.08 feet. The National Weather Service issued Flash Flood Emergencies for Wimberley and San Marcos (FEMA DR-4223).
- October 30–31, 2015: two-day rainfall reached 18.46 inches near Buda and 15.63 inches north of San Marcos (FEMA DR-4245).
- Halloween flood, October 30–31, 2013: 12 to 14 inches fell from Wimberley to Driftwood (FEMA DR-4159).
- October 17–18, 1998: the NWS estimated more than 30 inches of rain over a small area south of San Marcos in 36 hours (FEMA DR-1257).
Since 2015, the city has used federal HUD CDBG-DR funding for flood mitigation, including the Blanco River Flood Mitigation Project. Our San Marcos flood claims article covers the history and the claim process in more depth.
Flood Maps and NFIP Coverage in San Marcos
The City of San Marcos participates in the National Flood Insurance Program. New FEMA flood maps covering the Blanco River, the San Marcos River, and portions of Sink, Purgatory, Willow Springs, and Cottonwood Creeks took effect on January 17, 2025, according to the city’s flood map revision page. If your property’s zone changed, your lender requirements and premium may have changed too.
Flood zones are about risk, not coverage. A home outside a mapped high-risk zone can still flood, and owners outside those zones are often not required by a lender to carry flood insurance.
What We Review and Document on a Flood Claim
| Area | What we look at | Why it matters |
|---|---|---|
| Policy declarations | Building and contents limits, deductibles, policy type | Determines what can be claimed and how much |
| Waterline | Measured height in each room, photographed with a tape | Drives drywall, insulation, and trim removal scope |
| Building systems | HVAC, water heaters, electrical panels, ductwork | Equipment is easy to overlook on a fast inspection |
| Contents | Room-by-room inventory with photos, ages, and values | Contents usually need their own detailed list |
| Mitigation | Extraction, drying, and tear-out records | Shows reasonable steps to limit further damage |
| Deadlines | Proof of loss date and any extensions | Missing a deadline can affect payment |
Common Issues With Flood Claims in Hays County
Flood versus other water
Rising water from outside is generally flood. A burst pipe or a roof leak is usually a homeowners claim. When a storm causes both, each insurer may point at the other, so documenting where the water entered is critical. See our water damage claims page for the non-flood side.
Strict proof-of-loss timing
NFIP policies require a signed proof of loss within a set period after the loss. Policyholders who wait for the adjuster’s report can run out of time.
Underestimated drying and tear-out
Slab-on-grade homes, common in San Marcos subdivisions, absorb water into drywall, baseboards, cabinets, and insulation. A scope that only replaces the lowest few inches may not match the actual waterline.
Depreciation on contents
Many flood policies pay contents at actual cash value, which reduces the payment for older items. Our RCV versus ACV guide explains the difference.
After the Water Recedes: First Steps
Flood cleanup is exhausting, and it is tempting to haul everything to the curb as fast as possible. A few steps help preserve the claim while you work:
- Wait until it is safe. Have utilities checked before turning power or gas back on, and wear protective gear; floodwater can carry sewage and debris.
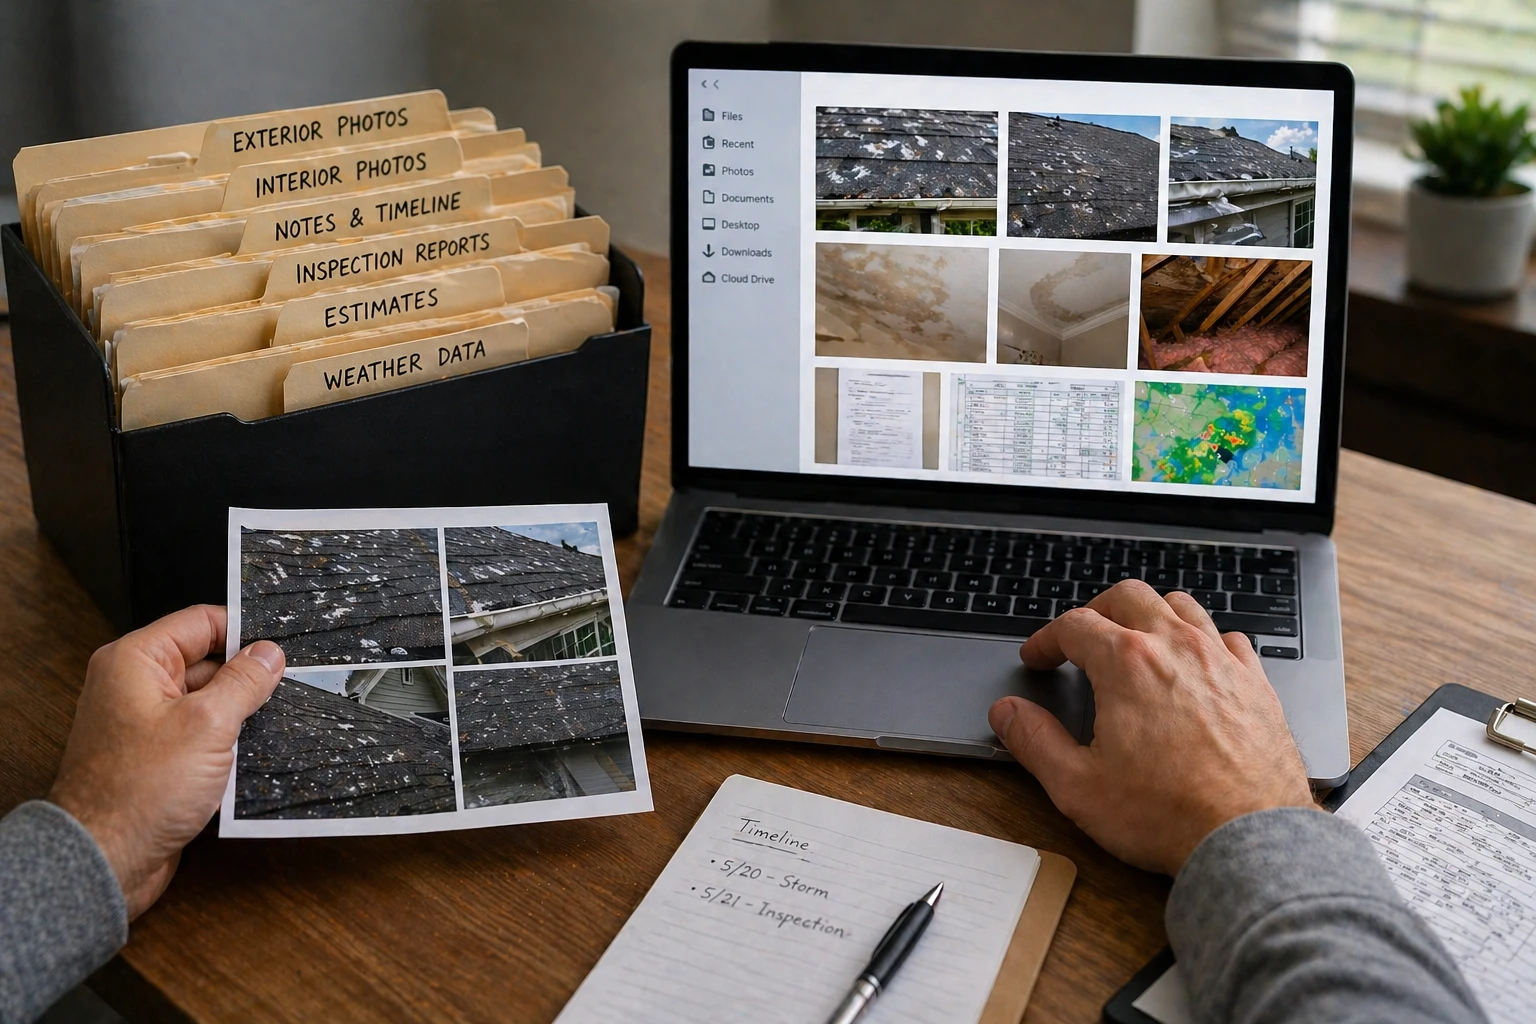
- Measure and photograph the waterline in every room, inside and out, with a tape measure visible in the shot.
- Report to your flood insurer right away and write down the claim number. If you also have wind or roof damage, report that separately to your property insurer.
- Photograph contents before disposal. Capture model and serial numbers on appliances and electronics, and keep small samples of carpet and flooring if possible.
- Start drying. Remove wet carpet, pad, and saturated drywall as needed to slow mold growth, and keep mitigation invoices and moisture logs.
- Calendar the proof-of-loss deadline as soon as you learn it.
Our claim documentation checklist is a helpful place to keep track as you go.
Our Flood Claim Process
- Confirm which policies apply and calendar every deadline.
- Document waterlines, damaged materials, and building systems before tear-out where possible.
- Build a contents inventory and a line-item building estimate.
- Prepare and submit the proof of loss with supporting documentation.
- Follow up with the flood adjuster and pursue additional payment requests when more damage is found.
If You Do Not Have Flood Insurance
Many owners discover after the fact that their homeowners policy does not cover rising water. Even then, it is worth reviewing the policy, because some damage from the same event, such as wind damage to the roof or a separately caused plumbing leak, may still fall under it. Federal assistance is only available when a disaster declaration includes individual assistance for Hays County, and it is not a substitute for insurance.
When to Call a Public Adjuster About Flooding
Consider calling a public adjuster in San Marcos if the proof-of-loss deadline is approaching and you do not yet have a complete estimate, if the flood adjuster’s scope stops below your waterline, if your contents list is overwhelming, or if your homeowners insurer and flood insurer disagree on the cause. If the same storm also brought wind or hail, our storm damage claims page explains how to handle both. For a no-cost first look, request a free claim review.
Frequently Asked Questions
Does my homeowners policy cover flood damage?
Usually not. Standard homeowners and commercial property policies generally exclude flood. Flood coverage typically comes from a National Flood Insurance Program policy or a private flood policy. Learn more at FloodSmart.gov.
How do I find out if my San Marcos property is in a flood zone?
The City of San Marcos offers an online GIS map and floodplain resources on its property insurance page, and FEMA’s Flood Map Service Center at msc.fema.gov shows official maps. New maps for the Blanco River, San Marcos River, and parts of several creeks took effect January 17, 2025.
Is there a waiting period for new flood insurance?
NFIP policies typically have a 30-day waiting period before coverage begins, with limited exceptions. That is one reason to review flood coverage before storm season rather than after a forecast.
What is a proof of loss in a flood claim?
It is a sworn statement of the amount you are claiming, with supporting documents. NFIP policies set a strict deadline for submitting it, so read the deadline in your policy and in any letters from the insurer, and ask for an extension in writing if you need one.
Are building and contents handled separately?
Yes. Flood policies usually carry separate limits and deductibles for building property and personal contents. If you only bought building coverage, furniture and belongings may not be covered.
Can I get FEMA aid and an insurance payment for the same damage?
Federal disaster assistance is generally not meant to duplicate insurance benefits, and it is only available when a declaration includes individual assistance for your county. Check with FEMA directly about your situation.
Can a public adjuster help with an NFIP claim?
Yes, a licensed public adjuster can help document and present a flood claim. Fees are disclosed in a written contract before any work begins; Texas law caps public adjuster compensation at 10% of the insurance settlement.