Key takeaways
- A public adjuster is a licensed professional who represents the policyholder, not the insurance company, on a property insurance claim.
- In Texas, public adjusters are licensed and regulated by the Texas Department of Insurance (TDI) under Insurance Code Chapter 4102. Always confirm the license before you sign anything.
- A Texas public adjuster contract must use TDI-approved terms, display “WE REPRESENT THE INSURED ONLY,” and give you 72 hours after signing to cancel.
- Fees are disclosed in a written contract before any work begins; Texas law caps public adjuster compensation at 10% of the insurance settlement.
- Hiring is a process, not a single phone call: gather your paperwork, verify the license, ask questions, read the contract, then sign only when you are comfortable.
If your roof was beaten up by spring hail or a pipe let go inside a wall, you have probably heard someone suggest calling a public adjuster. So what is a public adjuster, and how do you hire one without getting burned? This guide gives you the short definition, then walks through the hiring process in Texas one step at a time, from checking a license with the Texas Department of Insurance to reading the contract and using your 72-hour right to cancel.
It is written for homeowners and business owners in San Marcos, Hays County, and nearby communities such as Kyle, Buda, Wimberley, and New Braunfels. If you want the bigger-picture comparison of the different kinds of adjusters you may meet on a claim, see our companion article, What Is a Public Claims Adjuster?
What is a public adjuster? A plain-English definition
A public adjuster is a licensed insurance professional you hire to help prepare, present, and negotiate your own property insurance claim. The word “public” means the adjuster works for a member of the public, the policyholder, rather than for an insurance company.
That distinction matters because the adjuster your insurer sends, whether a company employee or an independent adjuster the insurer hired, is evaluating the claim on the insurer’s behalf. Many of those adjusters are fair and careful. But their client is the insurance company. A public adjuster’s client is you, and in Texas their contract has to say so in plain capital letters: WE REPRESENT THE INSURED ONLY.
In practical terms, a public adjuster typically:
- Reads your policy, including the declarations page, endorsements, deductibles, and exclusions, so the claim is built around the coverage you actually bought.
- Inspects the property and documents the damage with photos, measurements, and notes.
- Prepares a detailed, line-item repair estimate, often in Xactimate estimating software, the same platform many insurers use.
- Submits the claim package and communicates with the insurer’s adjuster.
- Compares the insurer’s estimate with the documented damage and asks for corrections or supplements when items are missing.
A public adjuster is not an attorney and cannot give legal advice, and Texas law does not allow a public adjuster to take part in repairing or rebuilding a property on a claim they are adjusting. If your situation turns into a lawsuit, a bad-faith question, or a deadline-to-sue issue, you need a Texas attorney.
How Texas regulates public adjusters
Texas has some of the more detailed public adjuster rules in the country, and knowing them is the best protection you have when hiring. The core rules come from Texas Insurance Code Chapter 4102 and TDI’s rules:
- Licensing. Anyone acting as a public adjuster in Texas must hold a public adjuster license issued by TDI.
- Approved contract. The contract must use terms approved by TDI and must include the statement “WE REPRESENT THE INSURED ONLY.”
- Right to cancel. You may rescind the contract within 72 hours of signing it.
- Fee cap. Compensation may not exceed 10% of the insurance settlement on the claim.
- Policy-limits rule. If the insurer pays or commits in writing to pay policy limits within 72 hours after the loss is reported, the public adjuster may not take a percentage fee and is limited to reasonable hourly compensation.
- No repair work. A public adjuster may not participate in the repair or reconstruction of the property on a claim they adjust.
TDI also publishes consumer guidance on what to know before you hire a public adjuster. It is worth a five-minute read before you sign anything.
How to hire a public adjuster in Texas, step by step
Here is the process we recommend to anyone in Hays County who is considering professional help with a claim. You can follow it whether you call us or someone else.
Step 1: Protect the property and report the claim
Your policy almost certainly requires you to give the insurer prompt notice of a loss and to take reasonable steps to prevent further damage. That means tarping an open roof, shutting off water, and drying out wet areas. Keep receipts for emergency materials and services. Take photos and video before cleanup where it is safe to do so. You do not need a public adjuster to report a claim, and waiting to report so you can “line someone up” first is usually a mistake.
Step 2: Gather your paperwork
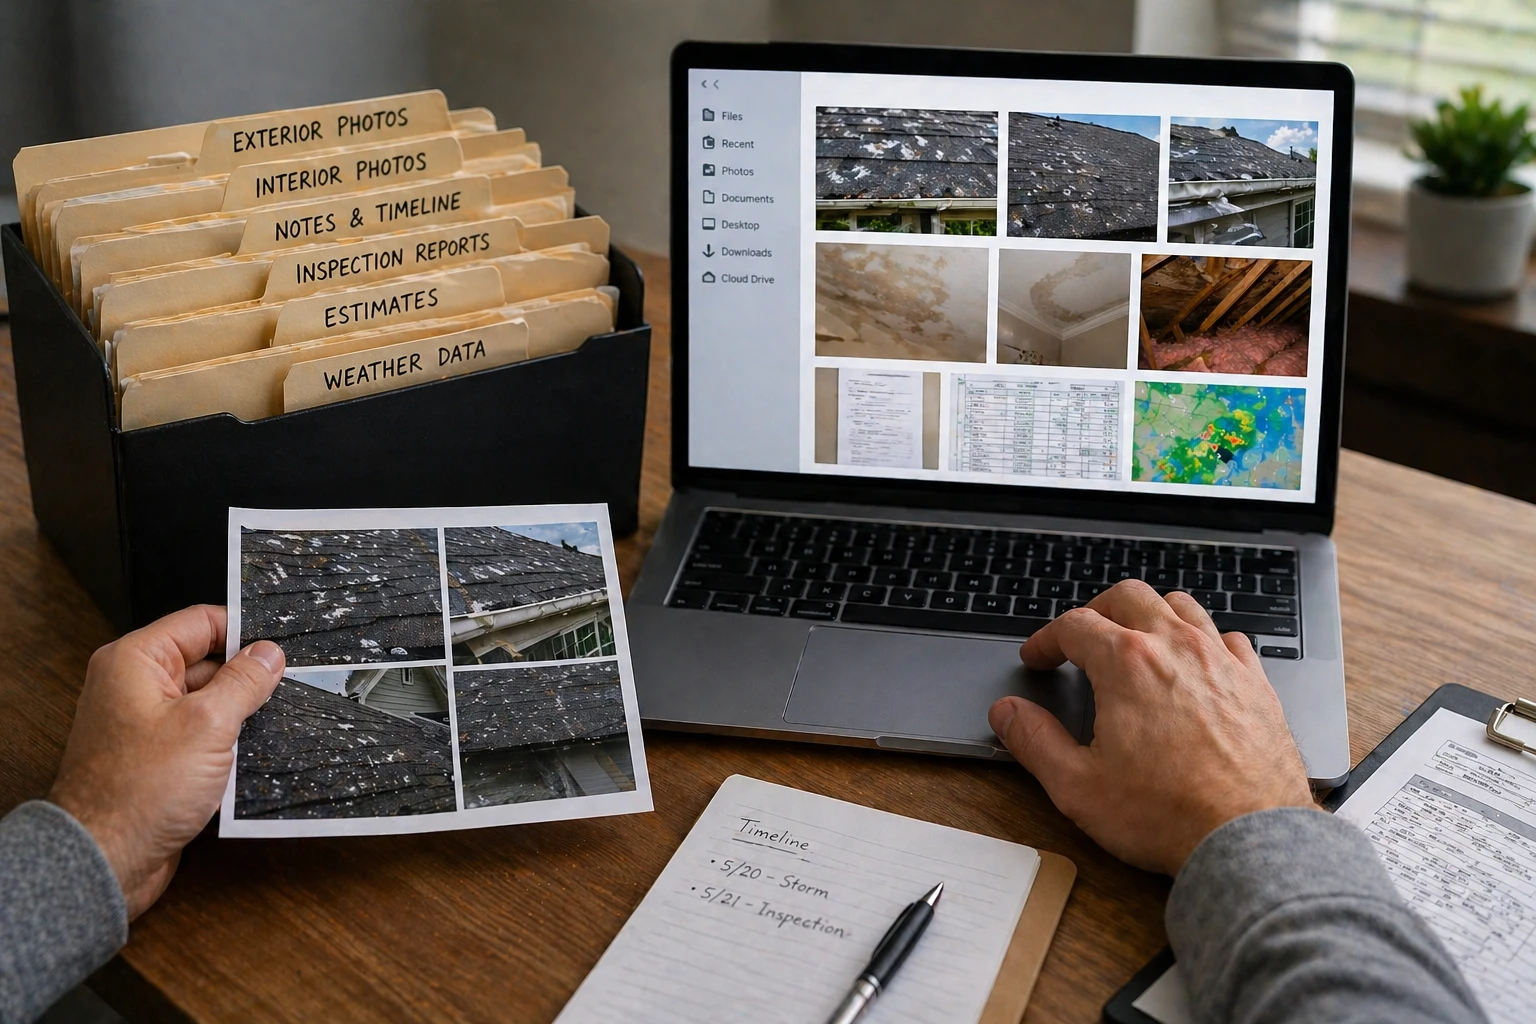
Before you talk to any adjuster, pull together the full policy (not just the declarations page), your claim number, any letters or emails from the insurer, the insurer’s estimate if you have one, contractor estimates, and your photos. Our claim documentation checklist lays this out item by item. Having it ready makes a consultation far more useful.
Step 3: Verify the license with TDI
Ask for the adjuster’s full name and Texas license number, then look it up yourself using the license search on the Texas Department of Insurance website. Confirm that the license is a public adjuster license, that it is active, and that the name matches the person you are dealing with. Our license number is 3356839, issued to Rise Public Adjusting LLC. A legitimate public adjuster will expect you to check and will not be bothered by it.
Step 4: Have a real consultation
A good first conversation is about your claim, not a sales pitch. Expect questions about what happened, when it happened, what the insurer has said so far, and what your policy covers. In return, you should get straight answers about how the adjuster would approach the claim, who will actually do the work, how communication will happen, and what the fee is. Our guide on how to find a public adjuster includes a full list of questions to ask and red flags to watch for.
Step 5: Read the contract line by line
The contract is where Texas law protects you, so read it slowly. Look for the items in the table below. If anything is blank, unclear, or different from what you were told on the phone, stop and ask before signing.
Step 6: Sign, then use your 72 hours
Once you sign, the clock starts on your 72-hour right to rescind. Use that window. Re-read the contract at home, talk it over with family or a business partner, and make sure the fee and scope match what you agreed to. If you change your mind, follow the cancellation instructions in the contract and keep proof of when you sent the notice.
Step 7: Know what happens next
After the contract is in place, your public adjuster will typically notify the insurer in writing that they are representing you, request the claim file, schedule an inspection, and start building the estimate. From there the work is documentation, communication, and negotiation, with you kept informed along the way.
Contract checklist: what a Texas public adjuster agreement should show
| Contract item | What to look for | Why it matters |
|---|---|---|
| Representation statement | “WE REPRESENT THE INSURED ONLY” printed on the contract | Required in Texas; confirms whose interests the adjuster serves |
| License number | Adjuster’s TDI license number, matching your own lookup | Only licensed public adjusters may represent you on a claim |
| Fee | A specific percentage or rate written in, at or below the 10% cap | Prevents surprises; Texas law caps compensation at 10% of the settlement |
| What the fee applies to | Clear language on which payments the fee is calculated on | Avoids disputes about money the insurer paid before you hired help |
| Right to rescind | Notice that you may cancel within 72 hours of signing, and how | Gives you time to reconsider without pressure |
| Claim details | Your name, property address, insurer, claim number, and date of loss filled in | Blank fields can be filled later by someone else |
| Signatures and copy | Both parties sign and you receive a complete copy | You need your own record of exactly what you agreed to |
One more practical point: insurance checks in Texas often list more than one payee, especially if you have a mortgage. Ask how payments will flow and how the fee will be handled when a check also names your lender. You want that explained before you sign, not after the first check arrives.
When hiring a public adjuster in San Marcos makes the most sense
Not every claim needs outside help. A small, clear-cut claim that the insurer handles quickly and fairly can be managed on your own, and we will tell you so. Professional help is more often worth considering when:
- The loss is large or complicated. A full roof, several rooms of water damage, a fire, or a commercial building with multiple systems involved.
- The insurer’s estimate seems far below repair costs. Missing rooms, missing roof components, or unit prices well below what local contractors are quoting. See our page on underpaid insurance claims.
- The claim was denied in whole or part and you believe the damage is covered. Our denied insurance claims page explains how a review works.
- The claim has stalled. Texas’s Prompt Payment of Claims law generally gives insurers 15 days after notice to acknowledge and begin investigating, and 15 business days after receiving requested items to accept or reject, with possible extensions. Repeated delays are worth documenting.
- You do not have the time. Running a business, caring for family, or living in a damaged house leaves little room for weeks of claim calls.
Local weather makes this question come up often here. NOAA’s Storm Events Database lists 180 hail reports in Hays County since 1967, with the busiest months in May and April. On May 9, 2024, storms dropped 3-inch hail at San Marcos Academy west of the city and 2.5-inch hail near the outlet mall, with wind gusts estimated at 70 mph (NCEI event record). Large, widespread events like that tend to produce the complicated roof, window, and interior claims where a careful estimate matters most. If you are still on the fence, our article Are Public Adjusters Worth It? works through the cost side with example numbers.
What a public adjuster cannot do
Understanding the limits is part of hiring well. A public adjuster in Texas cannot:
- Guarantee a result or promise a specific settlement amount. Coverage depends on your policy and the facts of the loss.
- Give legal advice, file a lawsuit for you, or tell you how a court would rule.
- Repair or rebuild your property on a claim they are adjusting, or steer you to a contractor in exchange for something of value.
- Change what your policy covers. A public adjuster can make sure covered damage is fully documented and priced, but cannot create coverage that is not there.
If anyone offering to “handle your claim” is unwilling to put these limits in writing, or if a contractor tells you they will negotiate with your insurer for you, treat that as a warning sign.
How we approach hiring conversations
San Marcos Public Adjuster is a public adjusting service of Rise Public Adjusting LLC, licensed by TDI (license 3356839), serving San Marcos, Hays County, and surrounding Central Texas communities. Articles on this site are written by Joseph Dittman, a licensed Texas public adjuster who is also a certified insurance appraiser and insurance umpire, with a background that includes carrier-side adjusting and hands-on construction.
When you reach out, we start with a no-cost look at your situation. If your claim looks straightforward and fairly handled, we will say so. If it looks like you could use help, we will explain how we would approach it, what the contract says, and what the fee is, and then give you room to decide. That is how hiring a San Marcos public adjuster should feel: informed, unhurried, and on your terms.
To get started, request a Free Claim Review, call +1 (832) 503-5866, or email info@sanmarcospublicadjuster.com. You can also learn more about our San Marcos public adjuster services or read about us first.
Frequently Asked Questions
Does a public adjuster replace my insurance company’s adjuster?
No. Your insurer still assigns its own adjuster, who evaluates the claim for the company. A public adjuster works alongside that process on your behalf, preparing your documentation and estimate and communicating with the insurer’s adjuster.
What should a Texas public adjuster contract include?
It should be a TDI-approved form, display “WE REPRESENT THE INSURED ONLY,” state the fee in writing, and explain your right to cancel within 72 hours of signing. Read every page before you sign, and do not sign a contract with blank fee or claim fields.
Can I hire a public adjuster if I already reported the claim?
Yes. Many people hire a public adjuster after the claim is open, often after the first inspection or estimate. The earlier you bring someone in, the more of the process they can help document, but an open claim is not a barrier.
How is a public adjuster paid in Texas?
Fees are disclosed in a written contract before any work begins; Texas law caps public adjuster compensation at 10% of the insurance settlement. If the insurer pays or commits in writing to pay policy limits within 72 hours after the loss is reported, the adjuster may not charge a percentage fee and is limited to reasonable hourly compensation.
Will I still talk to my insurance company after hiring a public adjuster?
You can. Your public adjuster will usually handle most of the day-to-day communication, but you remain the policyholder. You should still read what the insurer sends you and keep your own copies of everything.
Sources and further reading
This article is general information about property insurance claims in Texas, not legal advice, and not a promise of any coverage or outcome. Your policy language and the facts of your loss control your claim.